Lead economics
What a $40 Life Insurance Lead Really Costs per Closed Policy
A $40 lead costs $267 per closed policy at a 15% close rate—and $800 at 5%. Compare the math, exclusivity and replacement terms before choosing a life insurance lead vendor.
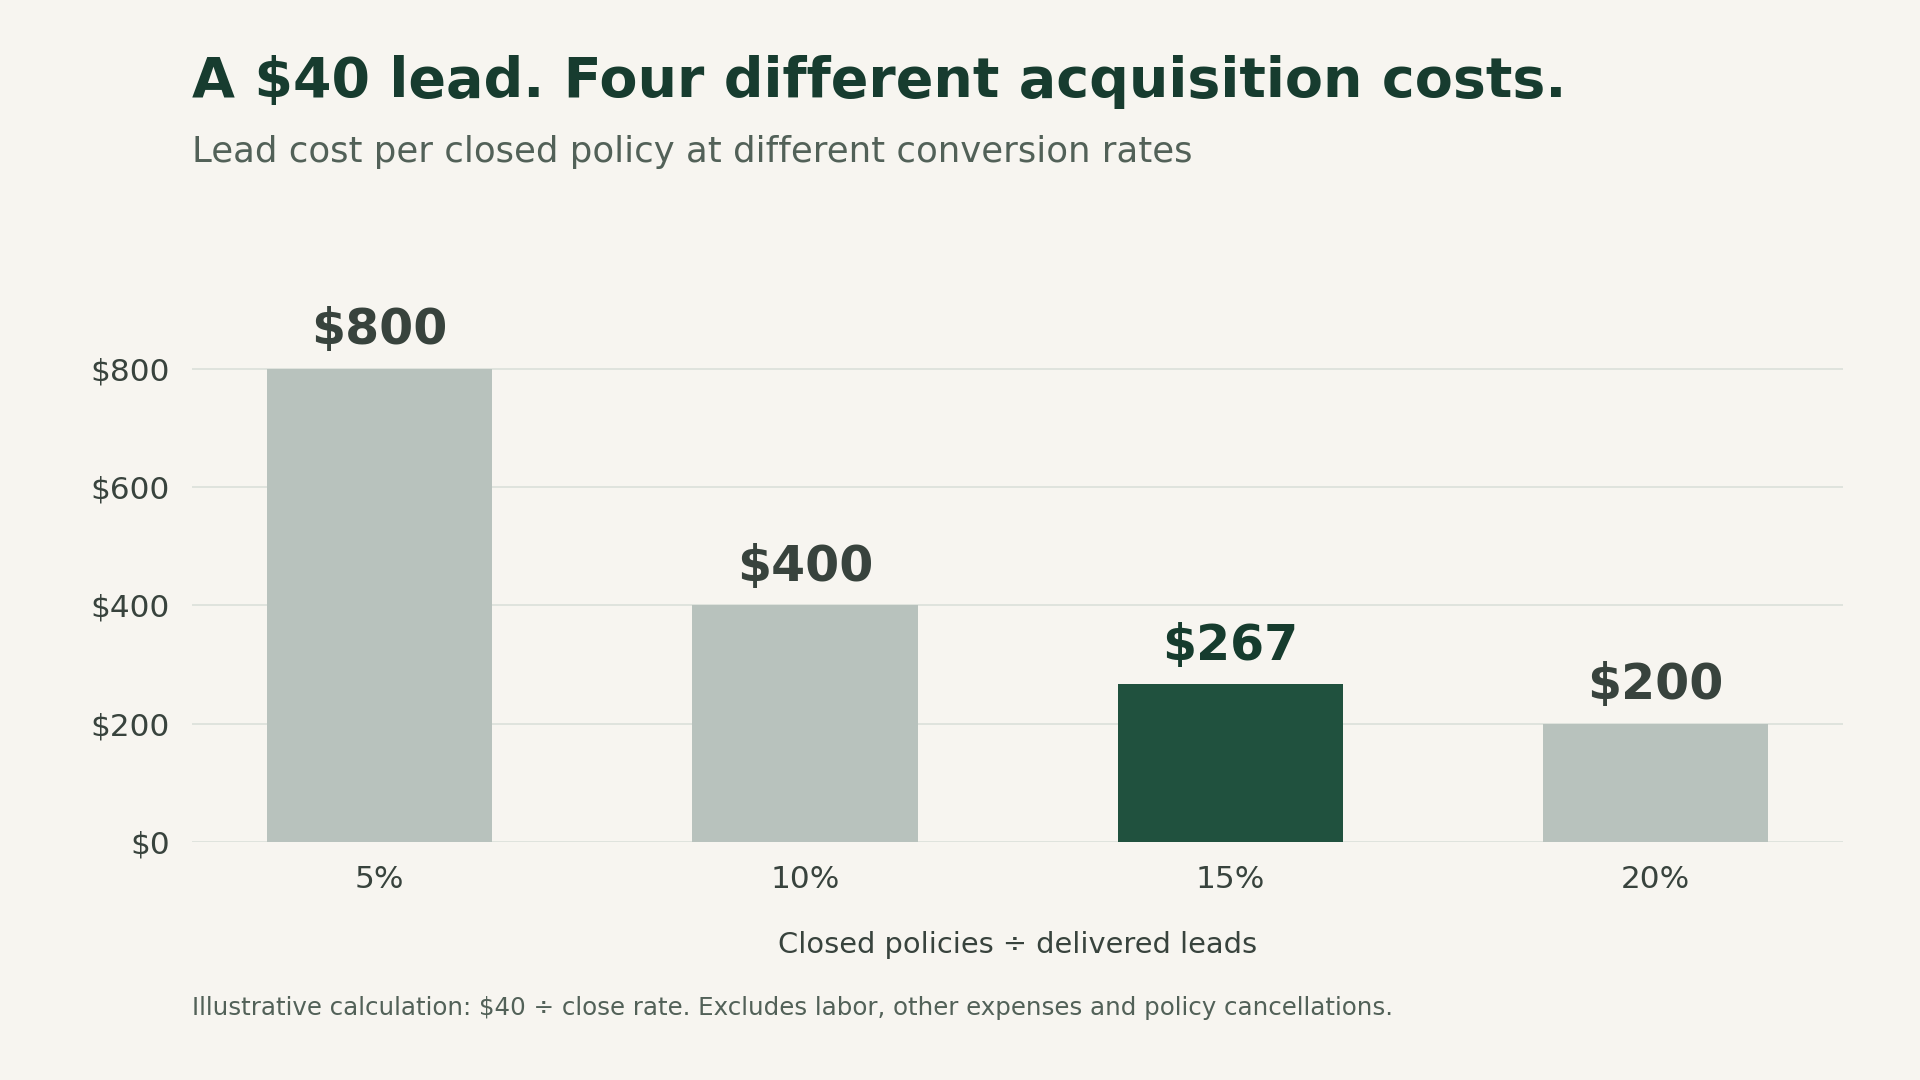
A $40 life insurance lead can cost an agency $267 per closed policy. It can also cost $800. The difference is the share of delivered leads that become policies.
That is a more useful starting point for comparing lead vendors than the sticker price alone. A lower-priced contact can still be the more expensive acquisition; an exclusive lead still has to produce a result. This analysis puts the calculation alongside the publicly described products from QuoteWizard and EverQuote and the current Ransom Life lead program.
The $40 lead: four possible outcomes
The table holds the purchase at 100 leads and $40 per lead. Only the close rate changes. These are calculated scenarios, not results from a 100-lead experiment.
| Close rate per delivered lead | Lead spend | Closed policies | Lead cost per closed policy |
|---|---|---|---|
| 5% | $4,000 | 5 | $800.00 |
| 10% | $4,000 | 10 | $400.00 |
| 15% | $4,000 | 15 | $266.67 |
| 20% | $4,000 | 20 | $200.00 |
The formula is simple: lead cost per closed policy = cost per lead ÷ close rate. Enter 15% as 0.15. This calculation includes lead purchases only; it excludes producer pay, software, follow-up labor and other operating costs.
The useful comparison is between two complete offers. A hypothetical $20 lead closing at 5% costs $400 per closed policy. A $40 lead closing at 15% costs $266.67. In that scenario the higher-priced lead produces a one-third lower acquisition cost. Those percentages are assumptions for the comparison, not a claim about another vendor.
Where Ransom Life fits
Ransom Life lists its current lead price at $40 and reports a 15% close rate per delivered lead, with $3,300 in average annual premium on the same policies. Its program offers one buyer per lead, a waitlist and unlimited bad-number replacement. The combination gives an agency concrete terms to evaluate: acquisition price, distribution and what happens when a number is unusable.
Applied to the illustrative 100-lead purchase, those inputs yield 15 closed policies, $49,500 in annualized premium and $266.67 in lead expense per closed policy. The $49,500 figure is policy premium. It is not agency revenue, commission received or profit.
Use the life insurance lead calculator to change the price, close rate and premium assumptions for your own buying plan.
What the competing products actually offer
| Program | Distribution described | Price information | Credit or replacement information |
|---|---|---|---|
| Ransom Life | One buyer per lead; waitlist | $40 per lead | Unlimited bad-number replacement |
| QuoteWizard Life | Exclusive life product delivered to one agent; daily and weekly caps | Request current product pricing | Qualifying lead-credit requests submitted online under its credit policy |
| EverQuote Life | Exclusive and shared options; its life guide describes a three-agent maximum for shared leads | Request current account/product pricing | Current general terms make refunds discretionary and set a ten-day charge-claim window |
QuoteWizard's life-specific product page explicitly describes one-agent delivery. Its broader distribution language should not be substituted for that product description. Its FAQ explains the credit-request process.
EverQuote describes both options in its life lead guide. Its current general terms define exclusivity within its platform and retain the company's right to contact or remarket to leads. Check the specific order and account terms before treating any general description as a purchase commitment.
Three details that change the comparison
Use the same denominator. Fifteen policies from 100 delivered leads is a 15% delivered-lead close rate. Fifteen policies from 50 contacted people is a 30% contact-to-policy rate. Both describe the same sales, but comparing them as if they were the same metric would double the apparent performance.
Count replacements consistently. A credit for future purchases and a replacement contact are different benefits. Record the original purchase, accepted invalid-number claims and replacement contacts separately. Ask whether any replacement is resold, whether there is a reporting deadline and what documentation is required. Do not silently remove unsuccessful leads from the denominator.
Follow the cash beyond the application. Record submitted applications, issued policies, paid policies and subsequent chargebacks separately. The same close-rate label can otherwise describe very different economics. Subtract lead expense and operating costs from commissions actually earned to evaluate profitability.
A repeatable way to choose
Run a bounded comparison with matching product types, territories, follow-up procedures and observation windows. Log delivery time, first contact attempt, policy status, annual premium, refunds or replacements and retained commission. Keep results grouped by the original delivery period so later policies do not inflate a newer batch.
Ransom's $40 price and reported 15% delivered-lead close rate create a clear proposition to test. The decision becomes stronger when an agency can see that combination in its own issued-and-paid records. Use the same calculation for every vendor: what did the leads cost, how many policies resulted, and how much commission remained?
Method
Product pages and terms were reviewed September 28, 2026. Ransom inputs come from its current lead program; a measurement period and cohort size were not provided. The tables model those inputs and alternative close rates using the displayed formulas. Competitor close rates, commission schedules and retention outcomes are not assumed. EverQuote's cited life-product guide was published in 2023; confirm current availability and order terms with the vendor.
Read the source material
Sources & references
- QuoteWizard: Life Insurance Leads agents.quotewizard.com
- QuoteWizard FAQ agents.quotewizard.com
- EverQuote: Best Life Insurance Leads for Agents learn.everquote.com
- EverQuote Pro Terms of Use & Conditions go.everquote.com
- Ransom Life: current lead program ransomlife.enterprises